Prices as of 1:42 PM Pacific. Every price is Monday's official close, and the Coil Engine figures are preliminary until the session settles tonight.
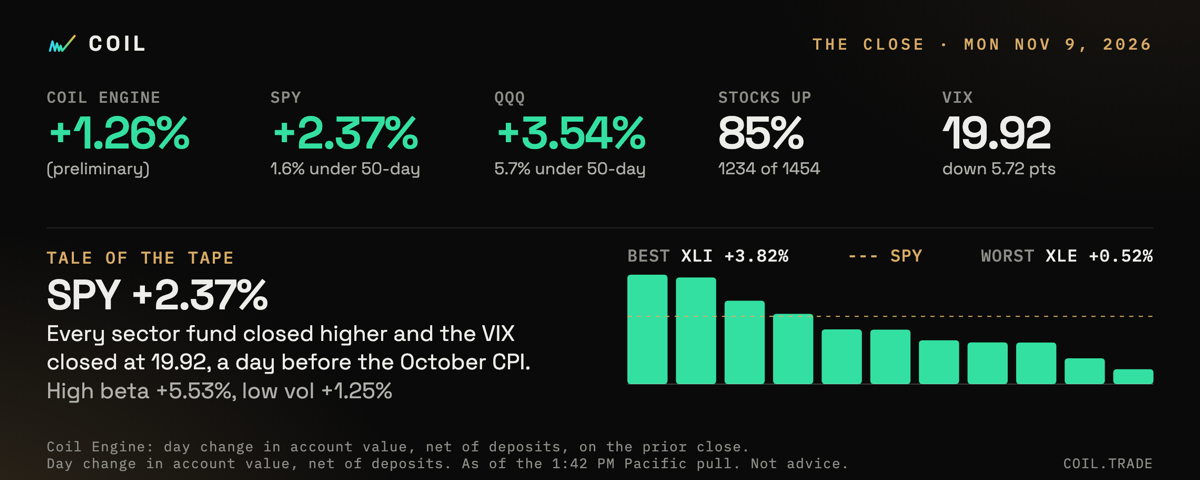
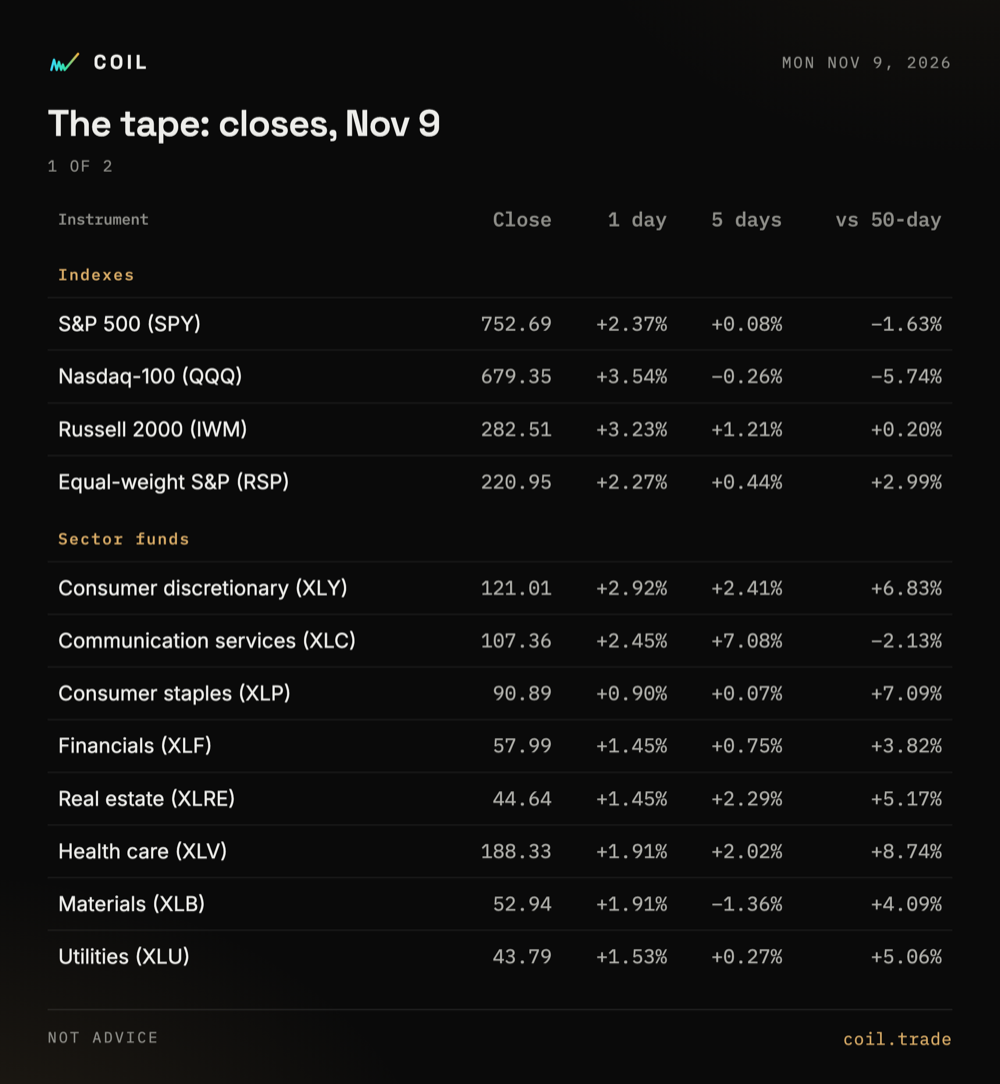
Every sector fund closed higher on Monday and SPY rose +2.37%, which puts it back to flat over five sessions. Most people will read that as the all clear after last Thursday. We read it as a relief bounce: the funds that led it are still the furthest below their 50-day averages, and the October CPI lands before Tuesday's open. We think the semiconductor fund ends the week below Monday's close, and the book spent the day selling health care and buying software.
What changed
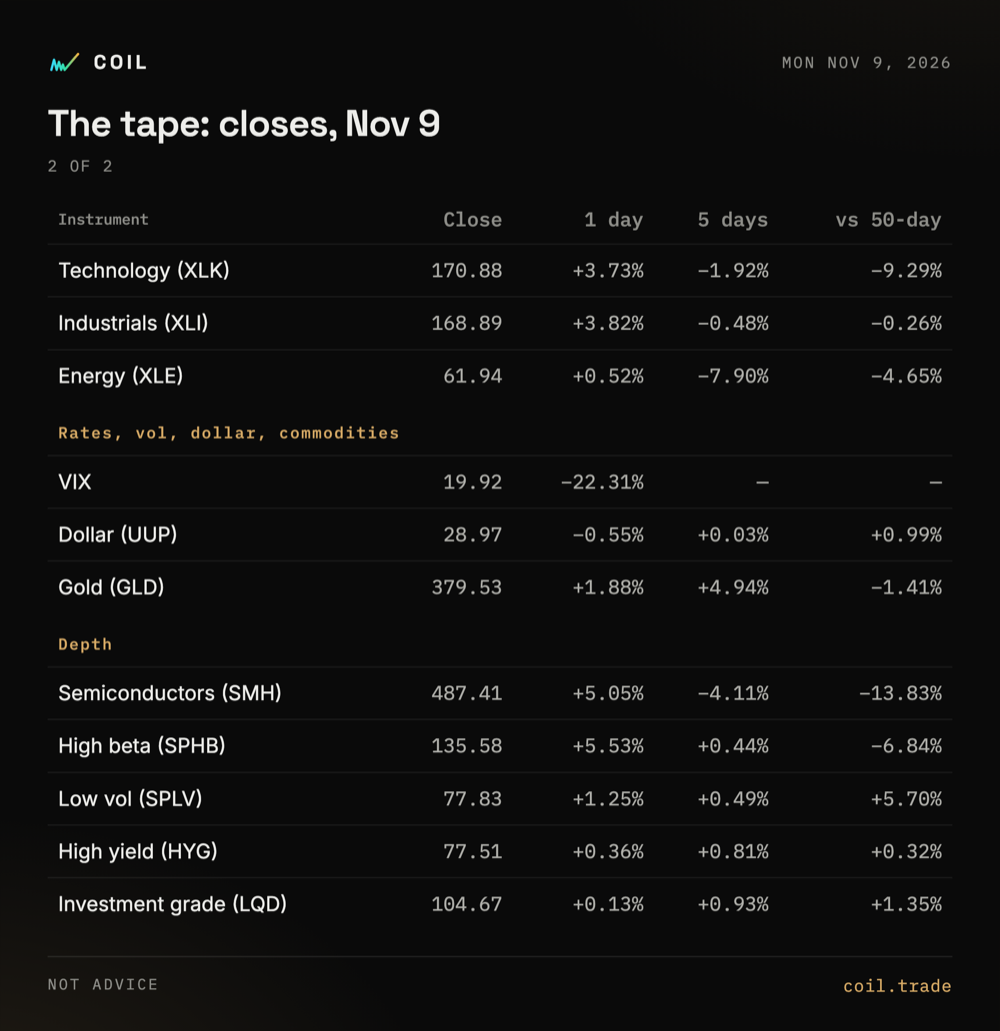
- Volatility came out fast. The VIX closed at 19.92, a one-day move of −22.31%. Fear left the market in one session, so Tuesday's print meets a market that has stopped paying for protection.
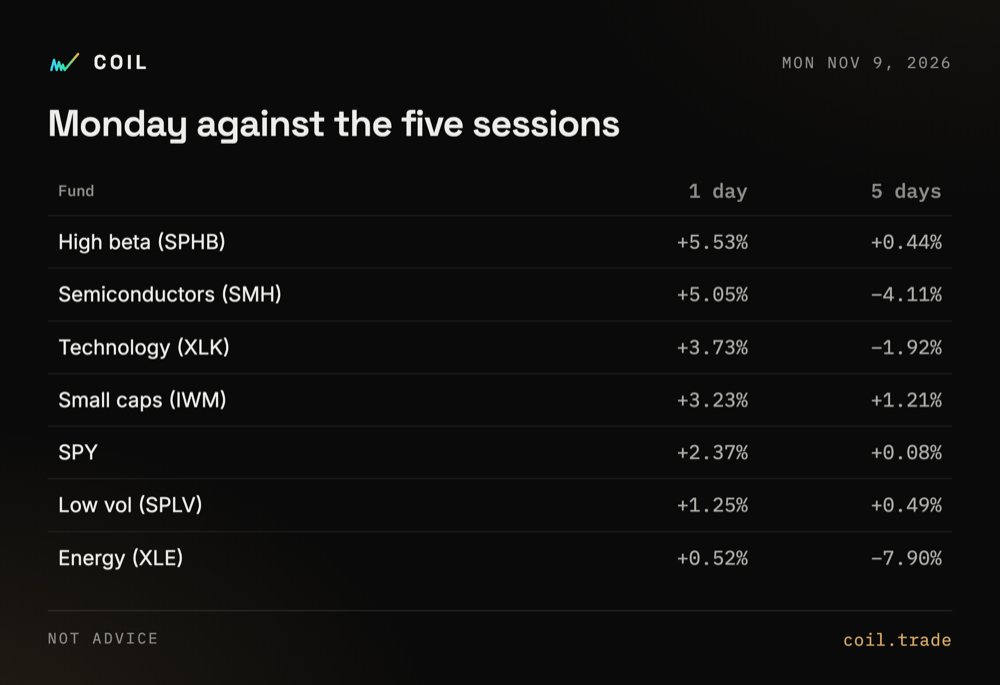
- The week's loss is gone in SPY and still there in the chips. SPY is +0.08% over five sessions. SMH is −4.11% over the same five, after rising +5.05% on Monday.
- Nothing was scheduled. The move came on position, and the first hard number arrives Tuesday.
The bounce paid in proportion to the damage
Rank Monday's gains and the list reads like last Thursday's losses turned over. High-beta stocks (SPHB) and the semiconductor fund led, with technology (XLK) close behind. At the other end sat low-volatility stocks (SPLV), energy and staples, which rose +0.90%.
A rally that rewards a fund for how far it fell is short covering and bargain hunting. It tells us sellers were finished for now. Whether buyers have changed their minds about what they want to own is a separate matter, and the 50-day averages still show what they wanted.
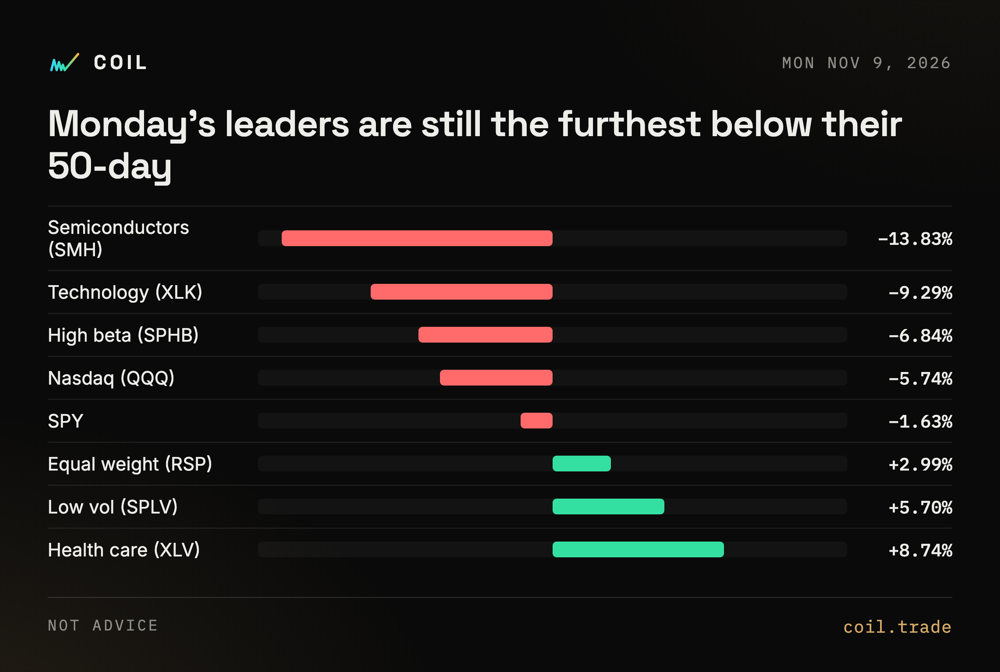
Health care, staples and low volatility are where the market has been comfortable, and one day did not change that. Those groups rose less on Monday, and they still sit well above their averages while the leaders of the day sit well below. The equal-weight index (RSP) is above its 50-day and SPY is below it, which says the average stock has held up better than the index its largest members drag.
Our own board gives the same answer from the bottom up. Of the 1454 names we score, 1234 closed higher, or 85%. The median Information Technology name on it rose 4.00% and 82% of them closed higher. In Industrials 89% closed higher. Energy was the one group where the rally thinned out: 61% of its names rose, with a median gain of 0.61%. Breadth that wide is a good sign for the market as a whole, and for the groups that led it the day is still a bounce inside a downtrend.
Credit did not join the celebration. High yield (HYG) rose +0.36% and investment grade (LQD) +0.13%. Credit also did not panic last week, so there was less to win back.
Why Tuesday's number carries more weight than usual
Expected against actual: none today. No major release was due on Monday.
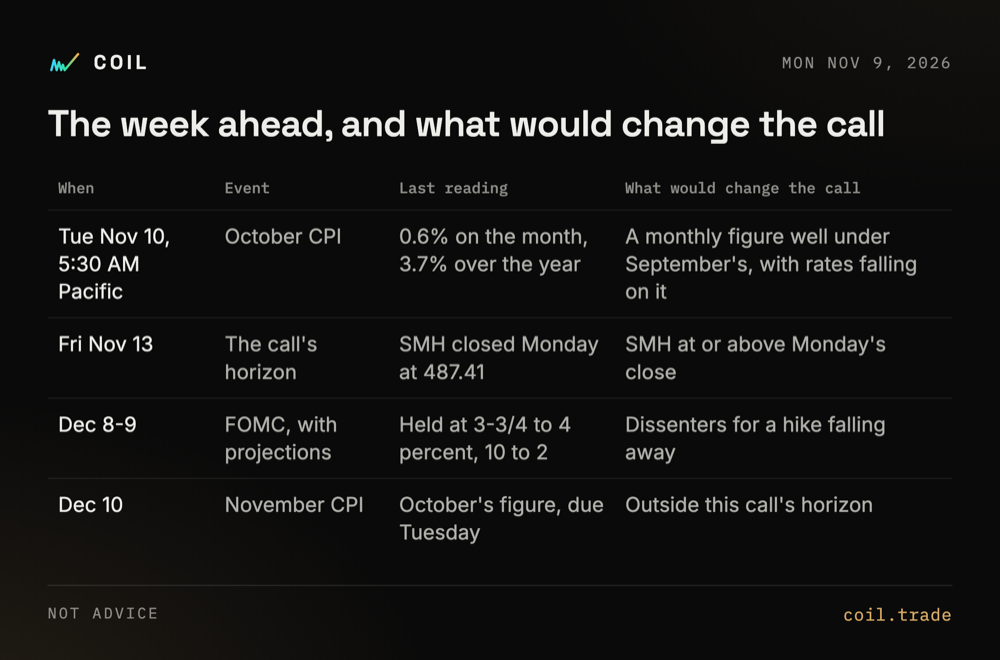
The read-through runs from prices to the Fed to the stocks that bounced. September's CPI rose 0.6% on the month and 3.7% over twelve months, with the core at 2.6%. Friday's jobs report showed payrolls up 165,000, against an average monthly gain of 48,000 over the prior twelve months, and unemployment at 4.1%. Hourly earnings rose 3.1% over the year, below the headline inflation rate, so real pay is falling while hiring speeds up.
The Fed held its target range at 3-3/4 to 4 percent on October 28 by a vote of 10 to 2, and both dissenters wanted an increase. Its next meeting is December 8-9 and comes with new projections. A firm CPI on top of a strong jobs report gives the dissenters their case, and the stocks most exposed to higher rates are the long-duration, high-beta names that led Monday.
The book: we sold health care into the rally
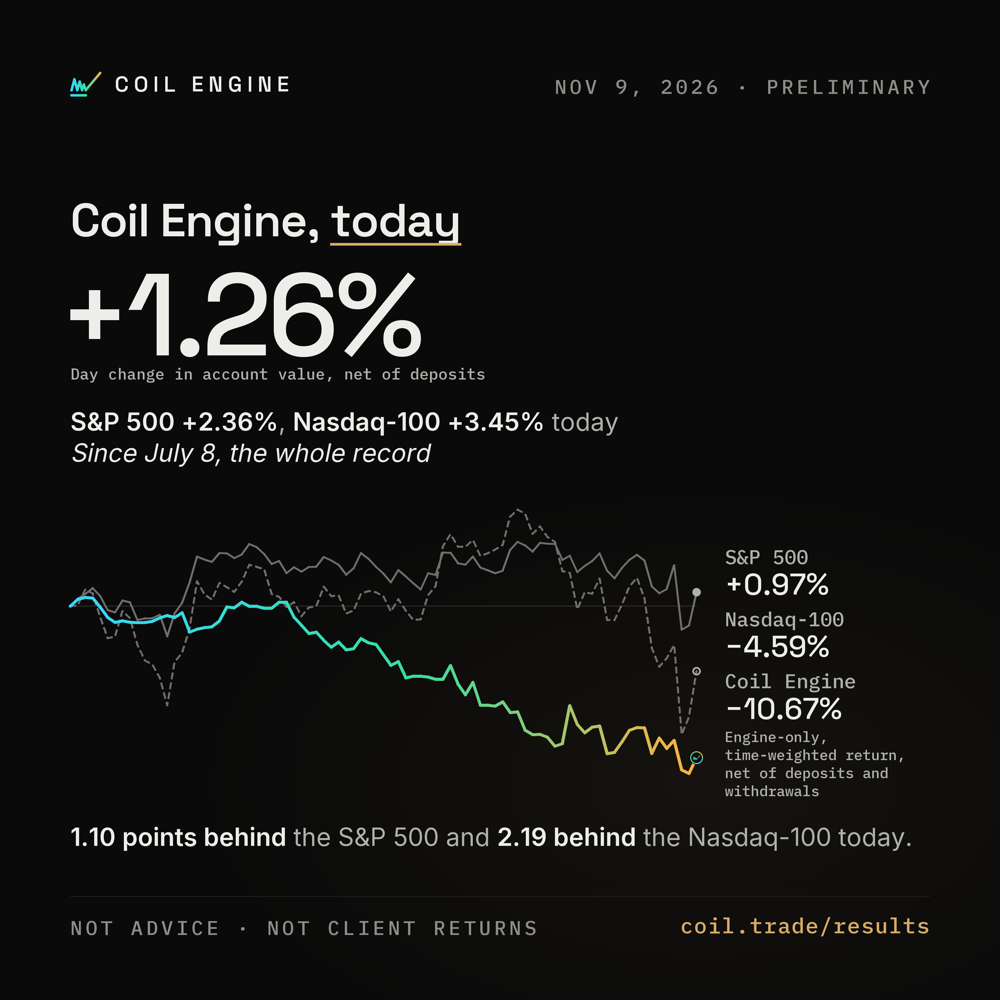
One decision ran the day. We came in holding mostly health care and defensives, and we closed 10 positions, 5 green and 5 red. BG at +4.08% and MEDP at +3.56% were the best. ELV at −1.52% and EBAY at −1.34% were the worst.
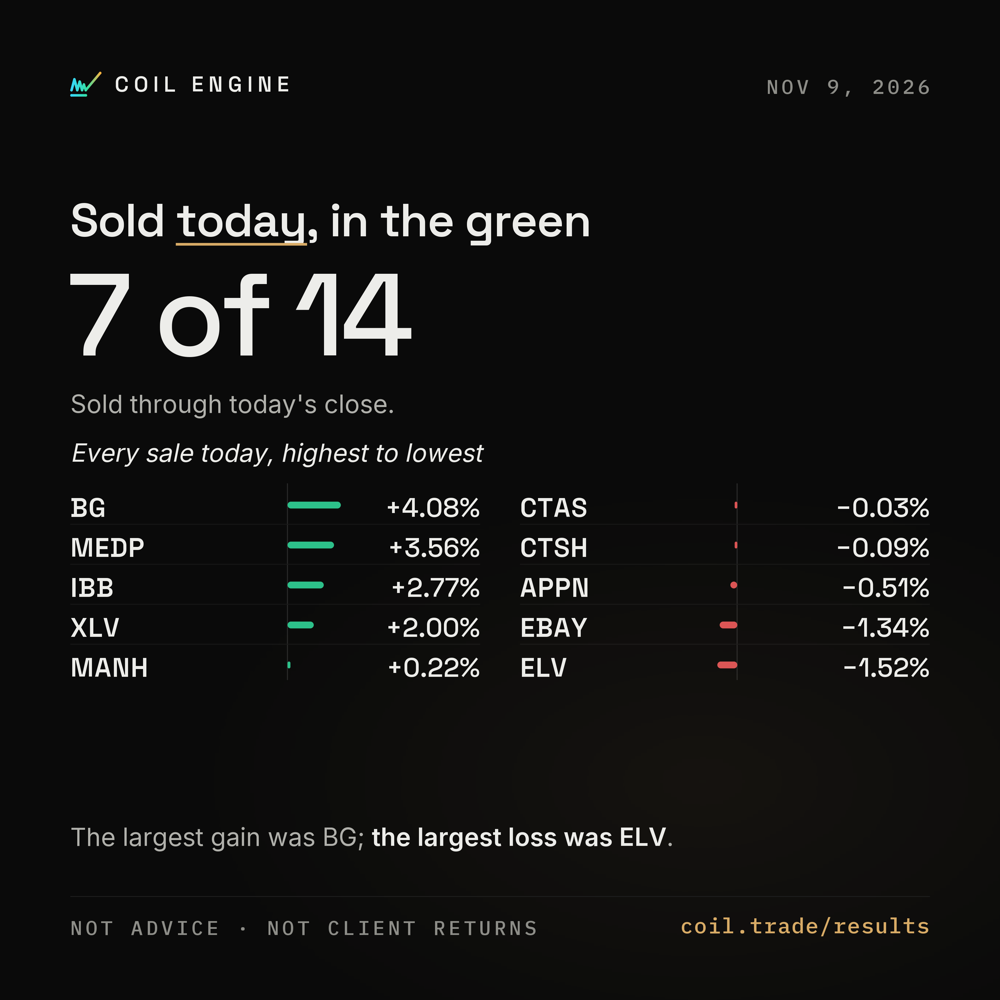
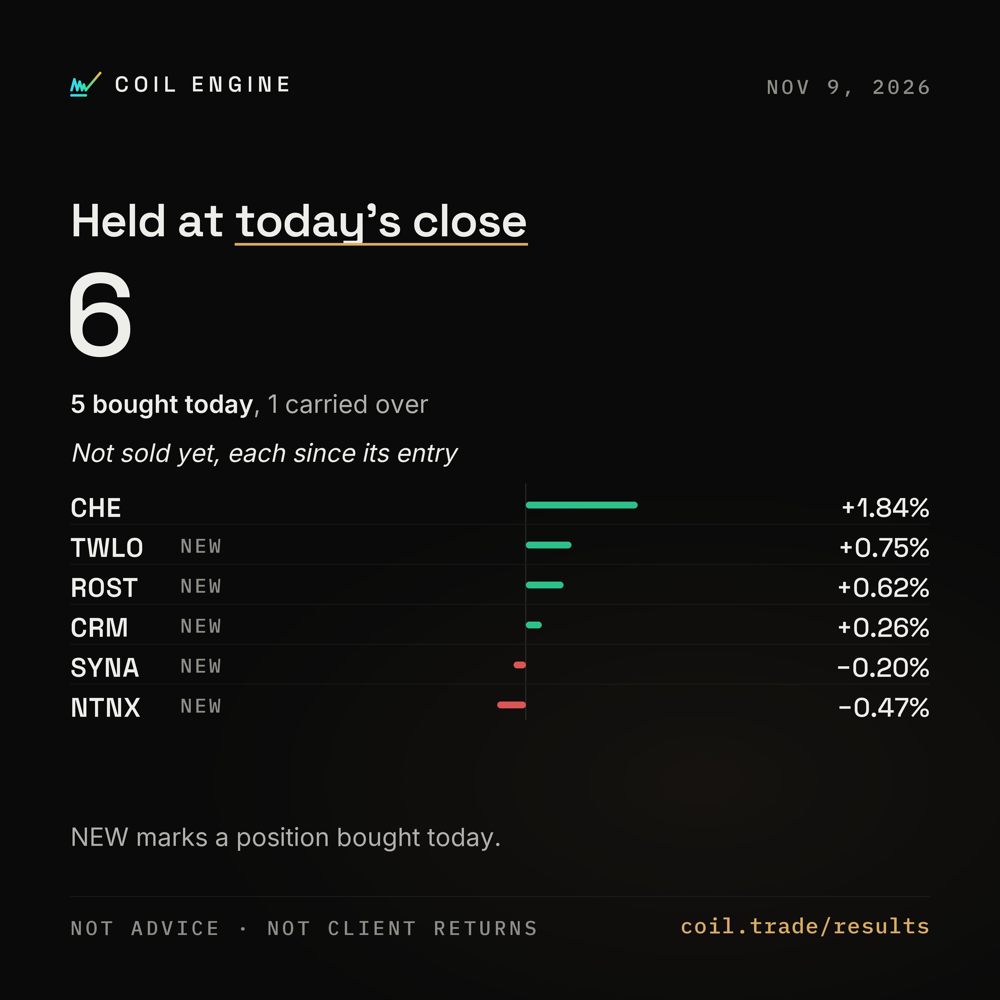
The mistake is in what we held when the bell rang this morning. A book built for last week's tape owned the groups that rose least on the day high beta rose +5.53%, so the book caught less of the rally than the index did by construction. Of the 5 names opened Monday, three are green at the close and two are red, all by less than one percent.
We carry CHE, CRM, NTNX, ROST, SYNA and TWLO, and the rest is cash.
Our call
The consensus reading of Monday is that Thursday was a washout and the low is in. The evidence for it is real: every sector rose, the VIX closed at 19.92, and small caps (IWM) are back above their 50-day. We agree the forced selling is over. Where we differ is on who leads from here. We do not think the groups that are −13.83% and −9.29% from their 50-day averages become leaders again in a week that opens with an inflation print and a Fed with two votes for a hike.
We think SMH closes below Monday's close of 487.41 on Friday, November 13. The tell is simple. SMH closes at or above 487.41 on Friday, November 13.
Two risks, as the other side would put them. First, a soft CPI removes the hike case in one morning, and the most oversold group in the market has the most room to run on that. Second, bounces off a washed-out low often last longer than a week, and a call against one can be right about the trend and wrong about Friday.
The book sits partly against this call. Four of the six names we carry are software or chip names, so a week that proves the call right would cost the book.
We came into Monday with no open call. Friday's call on SMH was graded on November 6 and held.
What's next
Keep reading
A day like Monday is easier to judge with a clear idea of what separates a bounce from a turn. We keep plain explainers on reading a tape, along with every close note and the Friday Wrap, at coil.trade/learn.
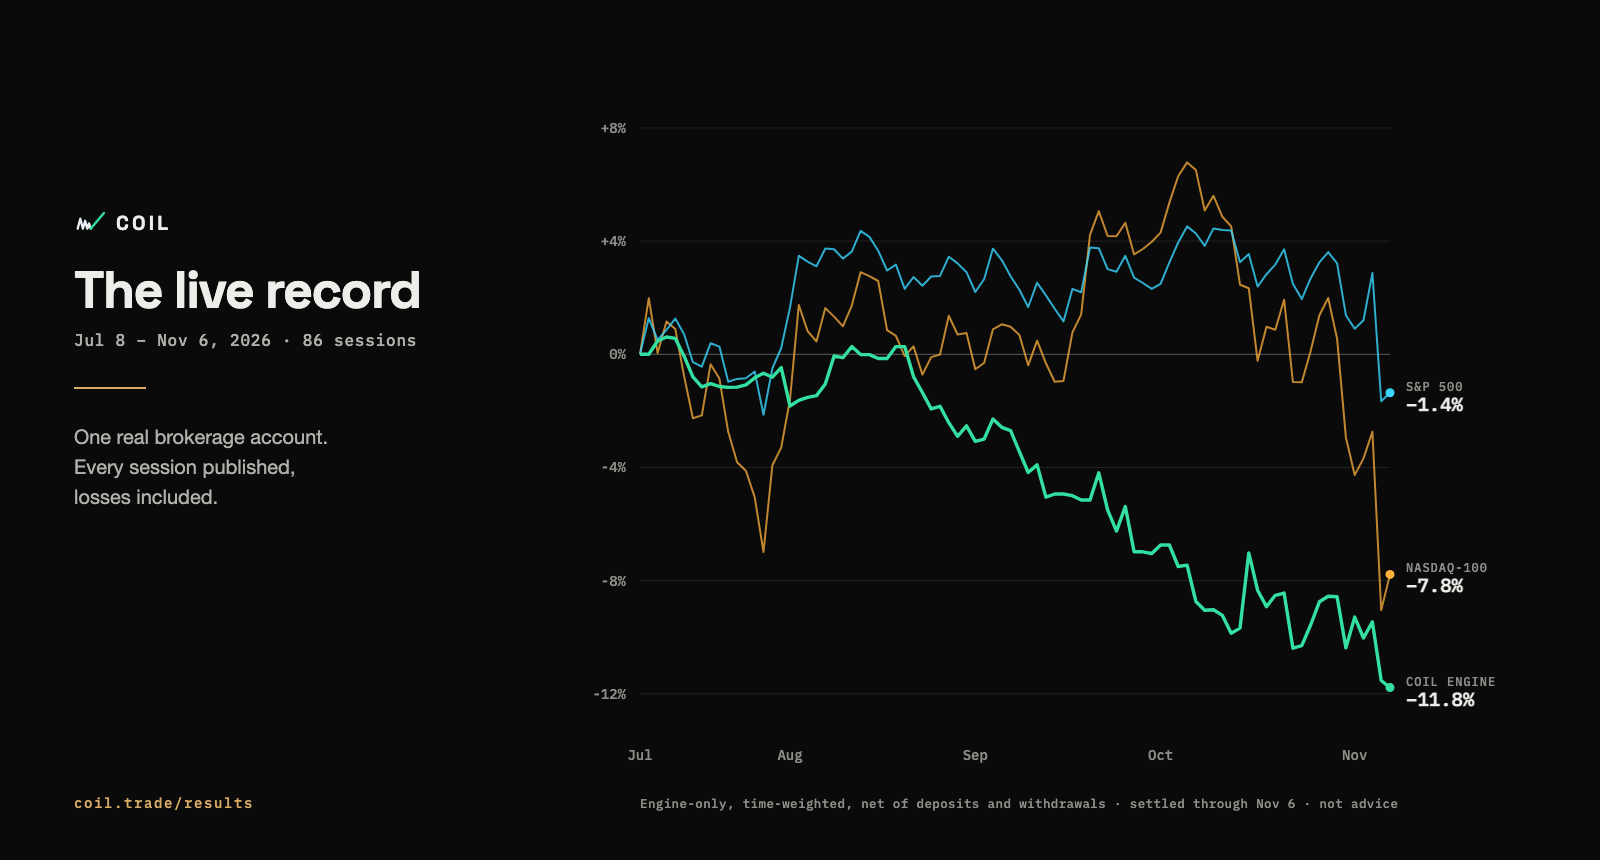
Our full record is at coil.trade/results.
Not advice.
COIL CLOSE is impersonal market commentary. It states a dated view of a market instrument, graded against its stated test, and is not investment advice, a recommendation or an instruction to trade, and is not tailored to anyone’s circumstances. Figures and prices are as of the time stated above.
Originally published at coil.trade on November 9, 2026.
About the author
- Coil (coil.trade) gives AI agents a trading desk's discipline: when to trade, when to wait, when to sit in cash. A scored board of 650+ US stocks and ETFs, free to any agent over MCP at mcp.coil.trade/mcp. Coil's own engine trades one real account and publishes every session at coil.trade/results, losses included. Research, not investment advice.
Comments
Join the discussionNo comments yet. Be the first to comment.